In-Network vs. Out-of-Network: Is Your Wesley Chapel Hospital Covered?
Find out which Wesley Chapel hospital accepts your insurance and how to dodge surprise bills with a quick network check.

Key Takeaways
- Check network status for your exact plan, not just the insurance company name, since one insurer can have different hospital networks across its plan types.
- Verify AdventHealth Wesley Chapel at 2600 Bruce B. Downs Boulevard in your insurer's directory, then call member services and record the representative's name and call reference number.
- A hospital that says it 'accepts your insurance' may only file claims for you; it does not confirm an in-network contract with your specific plan.
- Check every doctor separately, since surgeons, anesthesiologists, radiologists, and labs can be out of network even when the hospital is in network.
- If you carry a UnitedHealthcare of Florida plan, confirm access directly before scheduled care because AdventHealth Wesley Chapel's network status has been flagged as under negotiation.
- Federal No Surprises Act protections generally limit emergency care costs to in-network levels, but seek emergency care immediately and contact your insurer afterward for follow-up care rules.
You're standing in your kitchen, insurance card in hand, wondering a very reasonable question: which Wesley Chapel hospital does my plan cover? Maybe you're expecting a baby. Maybe a surgery is on the calendar. Or maybe you just want to know where to go if something goes wrong at 2 a.m. Whatever brought you here, you're asking the right question at the right time.
Here's the honest answer: there is no single list that fits everyone. The main hospital in town, AdventHealth Wesley Chapel, may be in network for one plan and out of network for another, even when both plans come from the same insurance company. The difference comes down to your exact plan, your network, and the date of your care.
This guide walks you through how to check, what the terms really mean, and how to avoid surprise bills. It is written for self-employed folks, families, and anyone shopping for coverage on their own. Let's make this simple.
The Short Answer: Meet AdventHealth Wesley Chapel
The main hospital located in Wesley Chapel is AdventHealth Wesley Chapel. It sits at 2600 Bruce B. Downs Boulevard, Wesley Chapel, FL 33544, and its main phone number is 813-929-5000. Many locals still remember it as Florida Hospital Wesley Chapel, before it took the AdventHealth name.
So when people ask which Wesley Chapel hospital their plan covers, this is usually the facility they mean. But whether your plan covers it at in-network rates is a separate question, and the answer depends on your policy, not just the logo on your card.
Why the Insurer's Name Is Not Enough
Many people assume that if a hospital works with an insurance company, it works with every plan that company sells. That is not how it goes. A single insurer may offer employer plans, Marketplace plans, private plans, and Medicare Advantage plans. Each one can have its own hospital network.
Think of it like a streaming service with different tiers. Same company, different channels. Your hospital access depends on which tier you actually bought.
In-Network vs. Out-of-Network: What Is the Real Difference?
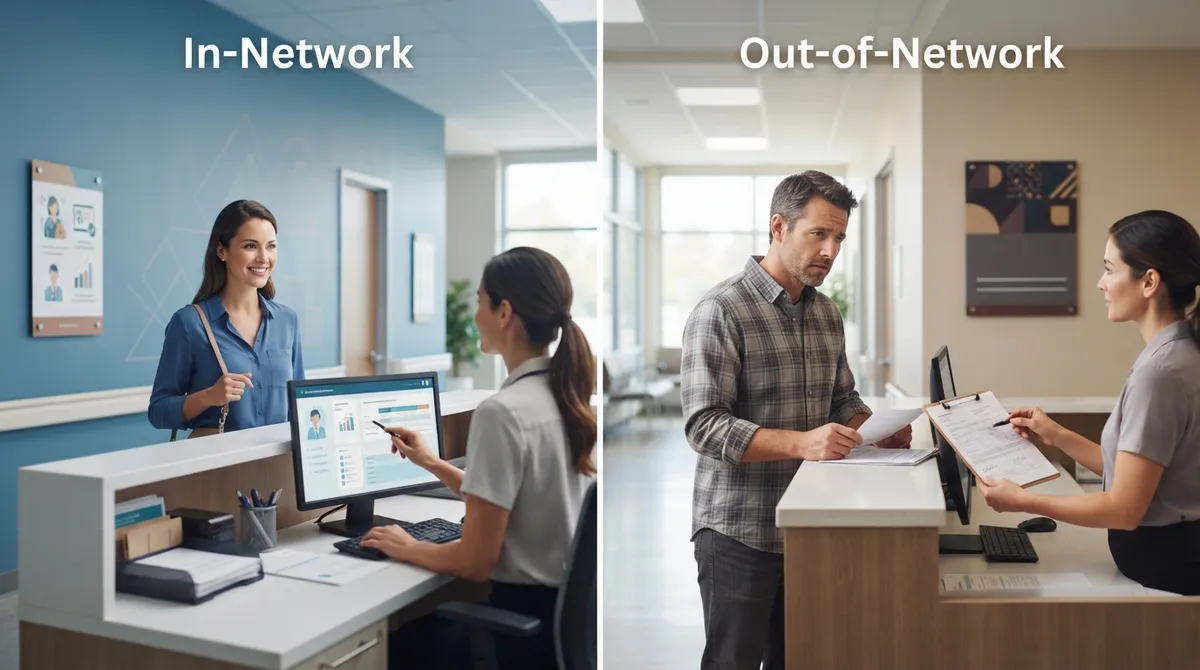
These two terms drive almost every hospital bill you will ever get. Here is how they compare side by side.
| Feature | In-Network Hospital | Out-of-Network Hospital |
|---|---|---|
| Contract with your insurer | Yes, rates are agreed in advance | No contract in place |
| Your cost share | Deductible, copay, or coinsurance at plan rates | Often higher, or may not be covered at all |
| Billing surprises | Fewer, though separate doctor bills can still happen | More likely, including balance billing in some cases |
| Out-of-pocket maximum | Usually counts toward your in-network limit | May have a separate, higher limit or none |
| Best for | Planned care like surgery, delivery, or tests | True emergencies or special approved situations |
The takeaway is simple. For planned care, staying in network almost always saves money and stress. If you want a deeper look at how limits work, our guide on your out-of-pocket maximum explains what protects you when bills pile up.
Hospital Accepts My Insurance vs. In Network
This one trips up a lot of people. A front desk may say, "Yes, we take your insurance." That can simply mean they will submit a claim for you. It does not always mean the hospital has a contract with your plan.
Only your insurer can confirm network status for your exact policy, because your insurer is the one that decides your benefits. The hospital's billing office can share which plans it works with, but treat that as a helpful hint, not the final word.
A Heads-Up About UnitedHealthcare of Florida Members
If you carry a UnitedHealthcare plan, pay extra attention. AdventHealth's Wesley Chapel pages currently flag ongoing negotiations with UnitedHealthcare of Florida that may affect access or coverage. Network contracts can change, sometimes with little warning.
That does not mean your plan is or is not covered today. It means you should confirm directly, using your exact plan and your exact date of service, before any scheduled care. This is also a good reason to review your coverage each year. Our checklist on things to check before you keep your plan in 2027 can help you spot network changes early.
How to Check Whether Your Plan Covers a Wesley Chapel Hospital
Good news: you can check this yourself in about 15 minutes. Here is the step-by-step approach.
- Grab your insurance card. Note your member ID, plan name, and the member-services phone number on the back.
- Sign in to your insurer's member portal. Use the provider directory while signed in so the search matches your exact plan, not a generic version.
- Search the facility by name and address. Look for AdventHealth Wesley Chapel at 2600 Bruce B. Downs Boulevard to make sure you pick the right location.
- Check each doctor separately. The hospital can be in network while your surgeon, anesthesiologist, radiologist, or lab is not.
- Call member services to confirm. Ask about network status for your specific service and date. Write down the representative's name and the call reference number.
- Ask about authorizations and costs. Find out if you need prior authorization or a referral, and what you would owe in deductible, copay, or coinsurance.
That call reference number is gold. If a bill ever looks wrong, it gives you something solid to point to.
Questions Worth Asking on the Phone
- Is AdventHealth Wesley Chapel in network for my exact plan on my date of service?
- Do I need prior authorization or a referral for this stay or procedure?
- What facility fees apply, and how do they interact with my deductible?
- Will I get separate professional bills from doctors, and are those doctors in network?
- Can you send the answers to me in writing or note the call in my file?
Watch Out for the Hidden Bills
Here is something many families learn the hard way. Even when the hospital is in network, the people treating you may bill separately. Anesthesiologists, radiologists, pathologists, and emergency physicians often work as independent groups.
That is why a planned procedure deserves a little homework. Ask the hospital and your surgeon which outside groups will be involved, then check each one with your insurer. A few phone calls beforehand can save you from a bill that feels like a punch in the stomach.
What About Emergencies?
Emergencies are different, and that is a relief. Under federal No Surprises Act protections, emergency services at covered facilities generally cannot be billed to you at out-of-network cost sharing. In most cases you pay what you would pay in network, subject to the rules that apply.
A few friendly cautions, though:
- This protection does not mean every later, non-emergency service is treated as in network.
- Follow-up care, a transfer, or a planned return visit may fall under different rules.
- Contact your insurer as soon as it is practical after an emergency visit.
If you ever think you are having a true emergency, go. Do not stop to check a directory first. Your health comes first, and the paperwork can wait.
Which Plan Type Gives You the Most Hospital Flexibility?
Different plan styles handle hospital choice differently. Here is a quick, general comparison. Remember, details vary by insurer and by plan.
| Plan Type | Hospital Choice | Typical Tradeoff |
|---|---|---|
| HMO | Usually limited to the plan's network, with referrals often needed | Lower premiums, tighter network |
| PPO | Wider network, some out-of-network coverage at higher cost | More flexibility, often higher premiums |
| EPO | In-network only, except emergencies, and usually no referrals | Middle ground on cost and choice |
| High-deductible plan | Depends on the network attached to the plan | Lower premiums, higher costs before coverage kicks in |
If you are weighing a bigger deductible to save on premiums, this walkthrough on whether a high deductible health plan is worth it can help you think it through.
Choosing a Plan With Your Hospital in Mind
If you are shopping for coverage, the best time to check your hospital is before you enroll, not after. A plan that looks cheap on paper can feel expensive if your preferred hospital or doctor is outside the network.
Here is a smart order of operations for different readers:
- Self-employed and freelancers: You are buying on your own, so network fit matters even more. Start with our look at Marketplace vs. private plans for freelancers.
- Families: Check the hospital, your pediatrician, and any specialists together. Our guide on choosing private health insurance for families in 2026 covers the big picture.
- COBRA transitioners: COBRA usually keeps your old network, which can be comforting. Compare it with other options in COBRA vs. Marketplace insurance.
- High-premium shoppers: Compare networks, not just prices. See how to choose between Marketplace vs. private health insurance.
One important note: medically underwritten private plans can involve health questions and benefit limits, so they are not identical to ACA-compliant Marketplace coverage. Comparing both side by side is the best way to see what you are really getting.
Estimating Your Costs Before You Go
Knowing the hospital is covered is step one. Knowing what you will owe is step two. Ask your insurer for a cost estimate for your specific service, and ask the hospital for its estimate too.
Look at your deductible, copay or coinsurance, and where you stand on your out-of-pocket limit for the year. If a baby, surgery, or major test is coming, a little math now helps you plan your budget with fewer surprises. You can also use Healthcare.gov to learn more about how Marketplace plans describe networks and cost sharing.
Local Help for Wesley Chapel Residents
Reading plan documents can feel like decoding a secret language. If you would rather talk it through, that is exactly what Baker Health Solutions is here for. Austin Baker is an independent agent who compares private and Marketplace options side by side, with your doctors, prescriptions, budget, and household in mind. He explains things in plain English, with no pressure, and stays available after you enroll.
If you live in or near Wesley Chapel, our guide on finding private health insurance in Wesley Chapel, FL is a great next read. You can also see what neighbors say by checking Visit us on Google — Baker Health Solutions. Please keep in mind that no agent can promise provider access for every plan, so always confirm network status with your insurer before scheduled care.
Your Quick Pre-Visit Checklist
- Confirm the hospital is in network for your exact plan and date of service.
- Confirm every doctor and outside group involved is in network too.
- Ask about prior authorization and referrals.
- Get a cost estimate and write down your call reference number.
- Keep your insurance card and the member-services number handy.
Final Thoughts: Check First, Relax Later
So, which Wesley Chapel hospital does my plan cover? For most people, the question centers on AdventHealth Wesley Chapel, and the honest answer is that it depends on your exact plan, your network, and the date you need care. A quick portal search, one phone call to your insurer, and a few smart questions will give you a clear answer.
If you would like a friendly guide through it, Austin at Baker Health Solutions is happy to help you compare plans and check networks before you enroll. Request an online estimate or schedule a short, no-pressure conversation today, and walk into your next hospital visit with confidence.
FAQs
Q: Is AdventHealth Wesley Chapel in network with my health insurance plan?
A: It depends on your exact insurer, plan type, and network, so there is no one-size-fits-all answer. Sign in to your insurer's provider directory and search by the hospital's name and address, then call member services to confirm for your date of service.
Q: What is the difference between a hospital accepting my insurance and being in network?
A: A hospital that accepts your insurance may simply be willing to file a claim for you. Being in network means the hospital has a contract with your specific plan, which usually means lower, predictable costs. Your insurer is the best source for confirming network status.
Q: Can doctors at an in-network hospital still be out of network?
A: Yes, and it happens more often than people expect. Surgeons, anesthesiologists, radiologists, and labs can bill separately, so check each one with your insurer before planned care.
Q: What happens if I need emergency care at an out-of-network hospital in Florida?
A: Federal No Surprises Act protections generally limit your cost sharing for emergency services to in-network levels, subject to the rules that apply. Later non-emergency care may be treated differently, so contact your insurer as soon as you can.
Q: Do I need prior authorization or a referral for a hospital stay?
A: Many plans require prior authorization for planned stays or procedures, and HMO-style plans often require referrals. Call the number on your insurance card, ask what applies to your plan, and write down the reference number from the call.